AN EDUCATIONAL FINANCIAL FRAMEWORK
Your assets aren’t just pieces of a portfolio.

A portfolio is not a financial plan.
Investors are often described as aggressive, moderate, or conservative. Their portfolios are summarized as 80/20, 60/40, or 40/60. Those labels tell us what an investor owns. They don’t tell us what the money is supposed to accomplish.
01
One pool
Assets with different purposes and timelines are treated as though they have the same job.
02
One allocation
A single investment mix is applied across obligations with very different characteristics.
03
Unclear purpose
The relationship between the assets and the life they must support remains hidden.
Different money has different jobs.
Timing
immediate
Certainty
uncertain
Flexibility
low
Inflation
low
Consequence
high
Timing
intermediate
Certainty
moderate
Flexibility
moderate
Inflation
moderate
Consequence
moderate
Timing
long term
Certainty
flexible
Flexibility
high
Inflation
high
Consequence to current lifestyle
lower
The portfolio is the financial plan expressed through assets.
Define future spending, goals, and obligations.
Assess timing, certainty, flexibility, inflation, and consequence.
Determine how much risk the financial structure can withstand and how much return is actually required.
Select assets whose characteristics align with the obligation.
Review and revise the matches as markets, priorities, and life circumstances change.
Markets are unpredictable. Your life is more knowable.
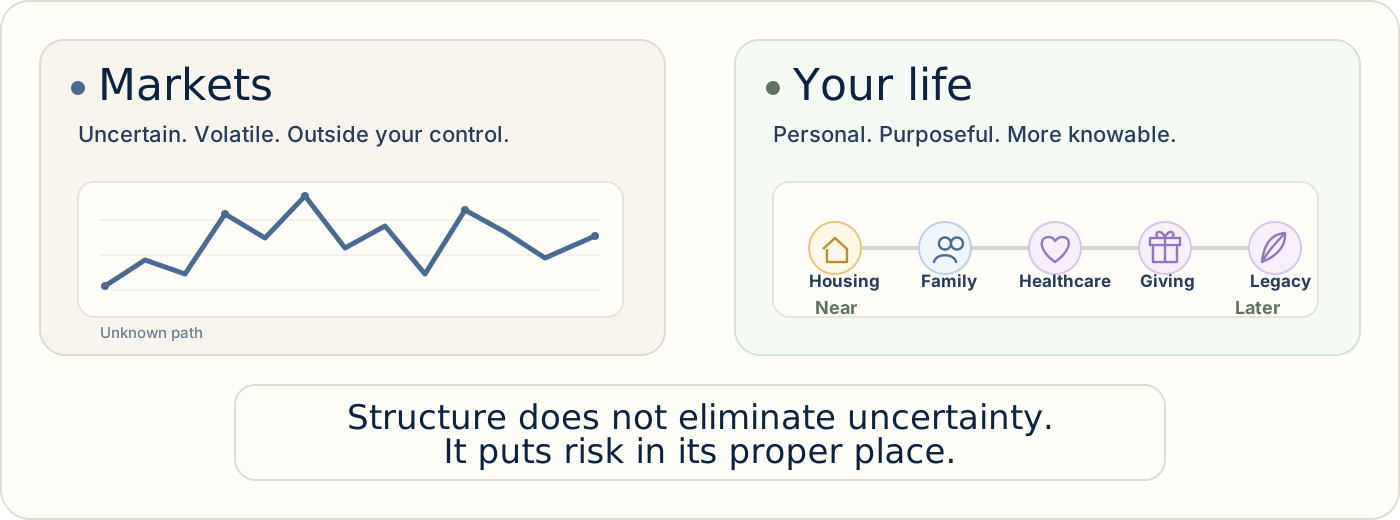
Clarity can change behavior.
Asset Life Matching in real life
Retirement is not one liability. Different years of retirement create different spending needs, timelines, and levels of flexibility.
Changing careers, reducing work, or starting a business may require a dedicated financial runway.
Healthcare needs may be uncertain in timing but significant in consequence.
Planned gifts and charitable commitments can be aligned with appropriate assets, timing, and tax characteristics.
Assets intended for children, grandchildren, or future generations may have a longer life than assets intended for current spending.
Explore the applications →
More than a set of time-based buckets.
Timing
Certainty
Flexibility
Inflation sensitivity
Consequence
Financial risk capacity
Arbitrary time divisions
Treating every future expense equally
Relying only on subjective risk tolerance
Pretending risk can be eliminated
Forcing every investor into the same formula
Confusing the portfolio with the plan
Compare approaches →
The goal is to align your money with your life.
Developed through investing, planning, and real life.

Founder · Verbatim Financial
Continue exploring.
Read more →
Read more →
Read more →